The short answer.
Start by separating three questions: when you can qualify to buy, when your sale proceeds become available, and when you can physically move. Compare selling first, buying first, and coordinating both transactions with your agent and lender. The best sequence is the one your financing, contracts, cash reserves, and backup housing plan can realistically support.
Keep these points in mind
- Do not treat an expected sale price as cash already available for the next purchase.
- Coordinate two sets of contract deadlines, not just two closing dates.
- Put possession arrangements and fallback plans in writing with the appropriate professionals.
Buying and selling a house at the same time in Colorado requires careful planning, financial preparation, and coordination between two real estate transactions. Whether you are moving to a larger home, downsizing, relocating for work, or changing neighborhoods, managing both transactions can present challenges. Many homeowners depend on the proceeds from selling their current property to finance their next purchase. This makes timing particularly important, especially when mortgage approval, closing dates, and moving arrangements are involved.
Some homeowners prefer to sell before buying another house, while others want to purchase their next property before listing their current home. Each option has financial considerations and potential risks. Understanding how to buy and sell a house at the same time can help homeowners make informed decisions, avoid unnecessary expenses, and prepare for unexpected changes.
This guide explains how to coordinate buying and selling a home in Colorado, including financing options, home sale contingencies, closing arrangements, and important steps to consider.
Understanding the Process of Buying and Selling a House at the Same Time
Buying and selling simultaneously involves two separate property transactions that may depend on each other. The first transaction involves selling your existing home, while the second involves purchasing your next property. Both transactions have individual contracts, deadlines, financing arrangements, and closing requirements.
Why Timing Matters When Buying and Selling
Many homeowners plan to use the equity from their existing property as a down payment on their next home. However, those funds may not become available until the current property closes. If the sale is delayed, the purchase may also be affected. Closing dates, mortgage approvals, property inspections, and title requirements should be considered when planning both transactions.
A realistic schedule can help homeowners understand what needs to happen before they can complete their move.
How Colorado Housing Market Conditions Affect Your Plans
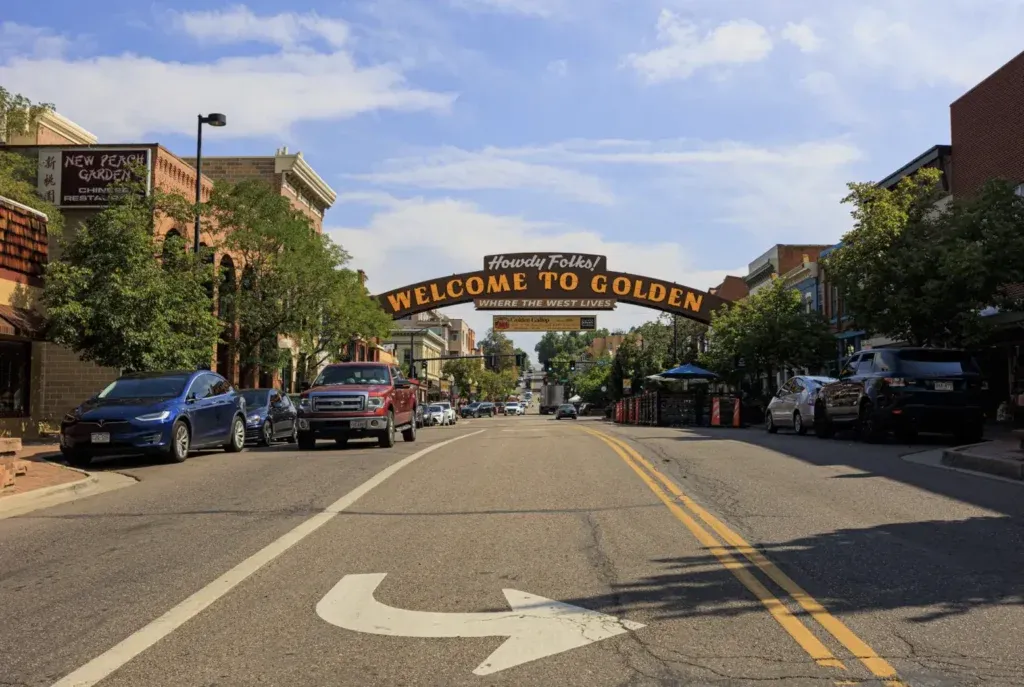
Local market conditions influence how quickly homes sell and how many replacement properties are available. When buyers have several properties to choose from, selling a home may require more competitive pricing. When available inventory is limited, finding a suitable replacement property may take longer. Conditions can also differ between Denver, Lakewood, Golden, Arvada, and surrounding Colorado communities.
Understanding both the market where you are selling and the market where you intend to buy is important.
Should You Sell Your House Before Buying Another?
Selling your current property before purchasing another home is a common approach. It may be particularly useful when the proceeds from the existing home are needed to finance the next purchase.
Benefits of Selling Your Home First
Selling first allows you to understand how much money is available from the completed transaction. You can calculate the final proceeds after mortgage payoff and applicable selling expenses. This may help establish a more realistic purchasing budget. Selling first can also reduce the risk of carrying two mortgages at the same time.
For homeowners with limited savings, avoiding overlapping property expenses may be an important consideration.
Challenges of Selling Before Buying
The biggest concern is finding somewhere to live after selling your current home. If you cannot complete your next purchase before moving out, you may need temporary accommodation. This can create additional expenses for rent, storage, and moving services. You may also feel pressure to purchase a replacement property quickly.
Planning for temporary housing can help reduce that pressure.
When Selling First May Be a Better Option
Selling first may make sense if you need your home’s equity for the next down payment. It can also be appropriate when carrying two mortgages would place significant pressure on your finances. However, the decision should reflect your household’s financial position and moving requirements.
Should You Buy a New House Before Selling Your Current Home?
Some homeowners prefer to purchase their next property before selling their existing house. This can provide more control over moving arrangements but may involve additional financial obligations.
Benefits of Buying Before Selling
Buying first allows you to secure your replacement property before leaving your current home. You may have more time to arrange moving services, complete necessary work, and prepare the new property. This can reduce the inconvenience of moving into temporary accommodation. It may also provide greater flexibility when searching for a property that meets your requirements.
Financial Risks of Buying First
Buying before selling may require enough income and savings to support two properties temporarily. Expenses may include mortgage payments, insurance, utilities, taxes, and maintenance. You may also need access to funds for the new down payment before the sale proceeds become available. If your existing home takes longer to sell than expected, these expenses can continue.
A lender should review your financing capacity before you commit to this arrangement.
When Buying First May Make Sense
Buying first may be appropriate for homeowners with sufficient financial reserves or approved financing arrangements. It can also be considered when finding a replacement property is a priority and the household can manage the associated costs. However, expected future sale proceeds should not be treated as immediately available funds.
How to Use Home Equity When Buying Another House
Home equity is an important financial consideration when buying and selling properties at the same time. Equity generally represents the difference between your property’s current market value and the outstanding debt secured by it.
Calculate Your Estimated Home Equity
Start by obtaining a realistic estimate of your current home’s market value. Then review your remaining mortgage balance and any other secured obligations. Estimated equity is the estimated property value minus those secured debts. It is not final sale proceeds; selling expenses and other obligations can reduce the amount available for your next purchase.
Understand Your Net Proceeds
Net proceeds represent the money remaining after paying the mortgage balance and applicable selling expenses. These expenses may include negotiated brokerage compensation, settlement charges, agreed concessions, and other obligations. An estimated net proceeds calculation can help you understand how much money may be available for the next property purchase.
The final figure depends on the actual selling price and transaction terms.
Review Your Financing Options
A mortgage lender can explain how your current mortgage and available equity affect qualification for another loan. Your options depend on income, debts, savings, credit history, and the requirements of the financing program. Early discussions can help identify whether selling first or buying first is financially practical.
Understanding Home Sale Contingencies in Colorado
A home sale contingency is a provision that may make a property purchase dependent on selling an existing home. It can be useful when a buyer needs proceeds from one transaction to complete another.
How a Home Sale Contingency Works
A homeowner may submit an offer on a replacement property that includes a condition related to the sale of their current home. The seller of the replacement property must agree to the proposed terms. The agreement may establish deadlines and other requirements that need to be satisfied. The exact protections depend on the contract language.
Why Sellers Review Contingent Offers Carefully
A seller may consider a contingent offer less certain when the buyer’s existing property has not yet sold. The buyer may need to list the property, find a purchaser, and complete the sale before the next transaction can proceed. This creates additional conditions that may affect closing. However, sellers evaluate offers based on the complete terms and current market conditions.
A contingent offer is not automatically unacceptable.
Understand Contract Deadlines
Real estate contracts establish important dates for inspections, financing, title matters, and closing. When two transactions are connected, homeowners should understand how delays in one agreement may affect the other. Contract deadlines should not be assumed to change automatically when a separate transaction is delayed.
How to Coordinate Two Real Estate Closings
Some homeowners attempt to complete their sale and purchase within a short period. This can reduce the time between moving out of one property and taking possession of another. However, coordinating closings requires attention to financing and settlement requirements.
Scheduling the Sale and Purchase
The existing home may need to close before the buyer can use the proceeds for the next purchase. Lenders and settlement professionals should understand the planned schedule. This can help clarify when funds are expected to become available. The transaction documents should reflect the agreed closing dates.
Preparing for Closing Delays
Unexpected delays can occur during mortgage underwriting, inspections, appraisals, and title review. If the first sale is delayed, the next purchase may also be affected. Homeowners should discuss possible alternatives before committing to a tightly connected schedule. Temporary accommodation or revised moving arrangements may be necessary.
Confirm Possession Dates
Closing and possession are not always the same event. The purchase contract establishes when the buyer is entitled to occupy the property. Some sellers negotiate additional time to remain in the home after closing. Any such agreement should clearly address occupancy dates and responsibilities.
What Is a Seller Rent-Back Agreement?
A seller rent-back agreement generally allows a homeowner to remain in the property for an agreed period after the sale closes. This arrangement may provide additional time to purchase another property or complete moving arrangements.
How a Rent-Back agreement Works
The buyer and seller agree on the terms of temporary occupancy. These may include the occupancy period, payment arrangements, insurance responsibilities, and property condition requirements. The agreement should be documented properly.
Benefits for Homeowners
A rent-back agreement may reduce the need for temporary accommodation. It can provide time to complete the next purchase or organize moving services. However, the buyer must agree to the arrangement.
Important Risks to Consider
Post-closing occupancy creates additional responsibilities for both parties. Insurance coverage, damage, possession deadlines, and other issues may need careful review. Professional legal and insurance guidance can be useful before accepting such an arrangement.
Understanding Bridge Loans and Other Financing Options
Some homeowners explore financing options that may help them purchase another property before selling their current home. These arrangements involve costs and qualification requirements.
What Is a Bridge Loan?
A bridge loan is generally a short-term financing arrangement intended to address a temporary funding need. Depending on the lender, it may provide access to funds while a homeowner transitions between properties. Bridge loans can involve higher borrowing costs and additional financial risk. The specific terms depend on the lender and loan structure.
Homeowners should review repayment requirements before using this option.
Using a Home Equity Line of Credit
A home equity line of credit allows eligible homeowners to borrow against available equity. Some homeowners consider this option when arranging a down payment before selling. However, borrowing against your property increases debt and may affect mortgage qualification. A lender can explain eligibility, repayment obligations, and any restrictions related to selling the home.
Compare Financing Costs Carefully
Short-term financing should not be evaluated only by the amount of money available. Interest expenses, fees, repayment terms, and financial exposure are important considerations. A qualified mortgage professional can help explain the available options.
Preparing Your Current Home for Sale
Proper preparation can help make the selling process more manageable. When buying another property depends on your current sale, delays in preparation may affect the broader moving schedule.
Request a Professional Home Valuation
Begin by understanding your property’s estimated market value. A Comparative Market Analysis reviews recently sold homes and relevant competing properties. This information can help establish realistic expectations about the potential selling price. It can also support financial planning for your next purchase.
Address Important Maintenance Issues
Review your property’s condition before listing. Visible problems involving plumbing, roofing, flooring, and other systems may need attention. Not every improvement is necessary. Consider the cost of proposed work alongside the property’s estimated market value and local competition.
Establish a Realistic Listing Timeline
Preparing a property may involve cleaning, repairs, photography, and marketing arrangements. Buyers may then require time for showings, negotiations, inspections, and financing. A realistic schedule should allow for uncertainty. Starting preparation early may provide more flexibility when searching for your next home.
Searching for Your Next Home While Selling
Finding a replacement property requires a clear understanding of your financial position and housing needs.
Determine Your Next Home Budget
Your purchasing budget should reflect realistic sale proceeds and financing options. Avoid assuming that your current home will sell for more than its estimated market value. Consider closing expenses, moving costs, and available financial reserves. A lender can help establish the financing amount you may qualify for.
Research Colorado Communities
Homeowners moving within the Denver metro area may consider Denver, Lakewood, Golden, Arvada, Littleton, and Centennial. Property types and available housing options vary by community. Researching current listings can help establish what may be available within your preferred budget.
Identify Your Main Property Requirements
Consider the number of bedrooms, bathrooms, parking spaces, and other features needed in your next home. Separate essential requirements from optional preferences. This can make the property search more practical when timing is important.
Common Challenges When Buying and Selling Together
Even with careful planning, connected real estate transactions can involve unexpected difficulties.
Your Current House Takes Longer to Sell
A property may remain on the market longer than expected because of pricing, condition, competition, or buyer demand. This can affect your next purchase if you depend on sale proceeds. Reviewing local market information and buyer feedback can help identify possible issues.
The Replacement Property Purchase Is Delayed
Financing, inspections, appraisals, and title matters can affect closing dates. If your existing home has already sold, you may need temporary accommodation. Understanding your contractual obligations can help you plan for this possibility.
You Receive an Offer With an Unfavorable Closing Date
A buyer may propose a closing schedule that does not match your moving plans. The offer should be evaluated based on its full terms. Negotiating an appropriate closing or possession date may be possible, depending on the buyer’s circumstances.
You Find a Home Before Your Current Property Sells
A suitable replacement home may become available sooner than expected. Before making an offer, confirm your available financing and understand any related contract conditions. Avoid committing to financial obligations based only on an assumed sale date.
Choose a sequence before choosing a moving date
Start with the constraint you cannot comfortably work around. It may be needing proceeds from the current property, avoiding two housing payments, or securing a particular type of replacement home. Write that constraint at the top of your planning document. Then discuss what would have to be true for each sequence to work, rather than assuming the transaction can be scheduled around a preferred weekend.
| Planning approach | Questions to answer first | Backup to discuss |
|---|---|---|
| Sell before buying | Where will you live, and how will you store belongings while searching? | Temporary housing and a realistic second move |
| Buy before selling | Has the lender evaluated the financing and carrying-cost scenario? | A longer-than-expected selling period |
| Coordinate both closings | Which transaction depends on funds or performance from the other? | A delay in funding, documents, or possession |
| Negotiate continued occupancy | Do the parties, lender, and insurer accept the proposed arrangement? | A clear move-out plan and contingency if plans change |
This is a discussion framework, not a claim that each option is available to every household. Ask your lender to evaluate your actual application and the financing products it offers. Ask your agent to explain which contract terms a buyer or seller would need to accept, and involve legal counsel where your arrangement needs individualized advice.
Use the sell-and-buy questionnaire to describe your timing, current property, and next-home priorities. Avoid submitting account numbers or sensitive underwriting documents through a general website form. Those belong in the secure process provided by the relevant professional.
Keep a cash calendar beside your transaction calendar
Create two separate timelines. The transaction calendar lists inspections, document reviews, objections or responses, financing, closing, and possession as stated in your agreements. The cash calendar lists when you expect money to leave or enter your accounts. A plan can look orderly on the first calendar and still be impractical on the second.
On the cash calendar, identify the purchase deposit, inspections or specialist visits, moving and storage expenses, any temporary housing, and the funds the lender or settlement provider says you must have available. Mark each item as a confirmed amount, an estimate from a provider, or a question still open. Do not use the expected sale proceeds to cover an earlier expense without confirming how the funds will actually be available.
The Loan Estimate explains proposed mortgage terms and estimated costs, but receiving it does not mean the lender has approved the loan (CFPB explanation of the Loan Estimate). Use that distinction when deciding whether a buy-first plan is ready to proceed. Get answers to outstanding underwriting questions directly from the lender before making commitments that depend on an assumed approval.
Keep the existing-home sale calculation separate from the new-home ownership calculation. The seller net-sheet tool helps organize your own selling assumptions, while the ownership-cost calculator helps compare your entered purchase assumptions. Neither replaces a payoff statement, lender decision, settlement statement, or professional valuation.
Plan for possession and delays without relying on a handshake
Discuss where everyone will be living at each stage, including pets, belongings, access devices, and utilities. Ask which event allows the next step to happen: signing, closing, funding, or the agreed possession time. Have the relevant professionals explain the distinction for your transaction instead of assuming that every milestone happens together.
Colorado’s official forms library includes a Post-Closing Occupancy Agreement as a separate transaction document (Colorado Division of Real Estate forms). If continued occupancy is part of your plan, ask your agent and legal adviser to address the terms in the appropriate agreement. Discuss the move-out date, payments, deposits, condition, access, insurance, and what happens if the occupant does not leave as agreed, without assuming a standard arrangement fits every situation.
Write a short delay plan before either closing. Decide who calls the movers, who confirms a new time with the other transaction team, where people can stay, and which expenses require fresh approval. Give every decision an owner and a contact method. That document should support your contracts, not attempt to change them.
Finally, review your replacement-home priorities before accepting a selling strategy that leaves little flexibility. Read the Denver buying guide for property due diligence and the seller preparation guide for the work you can organize in advance. The goal is one coordinated plan with realistic decision points, not a promised seamless outcome.
Frequently Asked Questions About Buying and Selling a House in Colorado
Can I Buy and Sell a House on the Same Day?
It may be possible to schedule both closings on the same day. However, funding and settlement requirements can affect timing. The arrangements should be confirmed with the relevant lenders and closing professionals.
Should I Sell My Home Before Buying Another?
Selling first may provide greater certainty about available proceeds and reduce overlapping mortgage expenses. Buying first may offer more flexibility for moving. The appropriate decision depends on your finances and housing needs.
Can I Use Equity From My Current Home to Buy Another?
Depending on your circumstances, home equity may be available through sale proceeds or certain financing arrangements. A lender can explain qualification and funding requirements.
What Happens if My Home Sale Falls Through?
The outcome depends on the contracts involved. If the next purchase depends on the sale, a failed transaction may affect your ability to complete the purchase. Reviewing contract provisions and obtaining professional guidance is important.
How Long Does It Take to Buy and Sell a House at the Same Time?
There is no fixed timeline. The process depends on market conditions, property preparation, buyer demand, financing, and closing requirements.
Can One Real Estate Team Help With Both Transactions?
A real estate team may assist with selling your existing property and searching for another home. This can support communication and coordination between the transactions. Representation agreements and responsibilities should be reviewed before proceeding.
Plan Your Home Sale and Purchase With Ed Prather Real Estate
Buying and selling a house at the same time in Colorado involves important decisions about financing, property values, contract deadlines, and moving arrangements. Understanding your current home’s market value and establishing a realistic purchasing budget can help you choose an appropriate approach. Ed Prather Real Estate assists homeowners throughout Denver, Lakewood, and surrounding Colorado communities with home selling, property searches, and coordinating their next move.
Whether you are purchasing a larger property, downsizing, or relocating within Colorado, having clear information about both transactions can help you make informed decisions.
Plan Your Next Move With Ed Prather Real Estate
Contact Ed Prather Real Estate to discuss your property valuation, home selling plans, and available housing options across Denver and Lakewood.
Make this advice personal.
Tell the team about your next move and get guidance for your situation.
This guide provides general planning information, not individualized legal, tax, insurance, or lending advice. Confirm the requirements, documents, deadlines, and costs for your transaction with the appropriate professionals.