The short answer.
Start by defining a comfortable ownership budget, discussing financing with a lender, and deciding what your daily life requires from a home. Then compare properties, investigate condition and documents, and work through the deadlines in your signed contract. A good first purchase is a home you understand and can plan to own, not simply the largest loan you can obtain.
Keep these points in mind
- Compare total ownership costs, not just asking prices or mortgage payments.
- Investigate the specific property and its documents before making assumptions about a neighborhood.
- Keep inspection, financing, title, closing, and possession questions on one shared checklist.
Buying a house in Denver, Colorado, is an important financial decision. Whether you are purchasing your first home, relocating to the city, or moving from a rental property, understanding the home buying process can help you make informed decisions. Denver offers different housing options, including single-family homes, townhouses, condominiums, and properties in established residential neighborhoods. Choosing the right home depends on your budget, preferred location, financing options, and long-term plans.
First-time home buyers in Denver should understand mortgage requirements, down payments, closing costs, property inspections, and local housing conditions before making an offer. A successful home purchase involves more than finding a property you like. Buyers also need to evaluate market prices, review contracts, and understand the responsibilities of homeownership.
This guide explains how to buy a house in Denver, CO, from preparing your finances and searching for homes to making an offer and completing the closing process.
Understanding the Denver Real Estate Market for Home Buyers
Before buying a home in Denver, it is important to understand local housing market conditions. Home prices, available inventory, mortgage rates, and buyer demand can influence the purchasing process. The Denver metro area includes communities with different property types and price ranges. Housing conditions in one neighborhood may be different from those in another.
How Denver Housing Market Conditions Affect Buyers
When more homes are available for sale, buyers may have additional options to compare. In markets with limited inventory, buyers may encounter greater competition for certain properties. However, the level of competition depends on location, property condition, asking price, and current demand. A well-priced property in a desirable location may attract interest even when the broader market has more inventory.
Understanding recent comparable sales can help buyers evaluate whether a property is reasonably priced.
Why Local Market Research Matters
Buyers should review recent home sales and available listings in their preferred neighborhoods. Comparing properties with similar characteristics can help establish realistic expectations. For example, the price of a detached home may differ considerably from a condominium in the same general area. A local real estate professional can help explain market conditions and available housing options throughout Denver and nearby communities.
Determine Your Home Buying Budget
Before searching for homes for sale in Denver, establish a realistic purchasing budget. The amount you can borrow is not necessarily the amount you should spend. Homeownership includes ongoing financial responsibilities beyond the monthly mortgage payment.
Review Your Income and Expenses
Start by reviewing your household income, existing debts, savings, and monthly expenses. Consider how much you can comfortably allocate toward housing while maintaining funds for other financial needs. A mortgage payment should fit within your broader budget. Buyers should also consider potential changes in household income or expenses.
Understand Monthly Homeownership Costs
Your housing expenses may include mortgage principal, interest, property taxes, homeowners insurance, and homeowners association fees. You should also budget for utilities, repairs, and routine maintenance. Some expenses can change over time, particularly insurance premiums and property taxes. Reviewing the full cost of ownership can help prevent financial pressure after purchasing a property.
Plan for Your Down Payment
A down payment is the amount paid toward the purchase price using your own funds or another permitted funding source. The required amount depends on the mortgage program and lender. Some mortgage programs allow qualified buyers to purchase with less than 20 percent down. However, a smaller down payment may affect mortgage insurance requirements, monthly payments, and borrowing costs.
Discussing available options with a mortgage lender can help determine what is appropriate for your financial situation.
Understanding Mortgage Options in Denver, CO
Most home buyers use mortgage financing to purchase residential property. Different loan programs have different qualification requirements, costs, and restrictions. Understanding the available options can help buyers compare financing arrangements.
Conventional Mortgage Loans
Conventional mortgages are commonly used for residential purchases. Qualification typically involves reviewing income, debts, credit history, and available funds. Down payment requirements vary depending on the loan program. Some borrowers may also be required to pay private mortgage insurance. A lender can explain the specific terms available to you.
FHA Home Loans
Federal Housing Administration loans are government-insured mortgages available to qualifying borrowers. These loans have particular credit, down payment, mortgage insurance, and property eligibility requirements. FHA financing may be an option for some first-time home buyers in Denver. However, buyers should compare the complete financing costs with other loan programs.
VA Home Loans
Eligible veterans, service members, and certain other qualifying borrowers may have access to mortgage loans backed by the Department of Veterans Affairs. Eligibility and lender requirements apply. Depending on the circumstances, VA loans may offer financing arrangements that differ from conventional mortgages. Buyers should confirm available terms with an approved lender.
Colorado First-time Home Buyer Assistance
Some Colorado buyers may qualify for homeownership education, down payment assistance, or financing programs. The Colorado Housing and Finance Authority, commonly known as CHFA, provides homeownership resources and works with participating lenders. Eligibility depends on program requirements, which may include income, loan qualifications, and home buyer education.
Program availability and terms should be verified before relying on assistance for a purchase.
Why Mortgage Preapproval Is Important
Mortgage preapproval is a useful step before making an offer on a home. It helps buyers understand their possible financing range and identify potential borrowing issues early.
What Happens During Mortgage Preapproval?
A mortgage lender reviews relevant financial information, which may include income, employment, credit history, debts, and available savings. Based on the review, the lender may issue a preapproval letter. This document generally identifies a potential borrowing amount subject to stated conditions. Preapproval does not guarantee final mortgage approval.
The lender may require additional documentation and review before closing.
Benefits of Getting Preapproved
Preapproval can help buyers focus on properties within an appropriate price range. It may also demonstrate to sellers that the buyer has taken steps toward arranging financing. However, buyers should still evaluate their monthly budget independently. A preapproval amount represents a financing assessment rather than a recommendation to spend the full amount.
Compare Different Mortgage Lenders
Mortgage offers can differ in interest rates, fees, loan terms, and monthly payments. Reviewing more than one lender can help buyers understand available financing options. The total cost of borrowing should be considered alongside the advertised interest rate. Ask lenders to explain fees, mortgage insurance, and any conditions that may affect the financing.
Choosing the Right Neighborhood in Denver
Selecting a neighborhood is an important part of buying a house in Denver. Different communities offer different housing styles, amenities, and property characteristics. The right location depends on your daily needs, preferences, and budget.
Consider Your Daily Commute
Travel time can influence your experience of living in a particular area. Consider the distance to employment, shopping, medical services, and other regularly visited destinations. Review transportation options and actual travel routes. A neighborhood that appears close to an important destination may still involve significant travel time.
Research Local Amenities
Buyers may consider parks, recreational facilities, restaurants, transportation, and other local services. Denver includes established residential neighborhoods as well as areas with newer developments. Local amenities can influence buyer preferences, but their importance varies from one household to another. Choose a location based on the factors that matter most to your everyday life.
Compare Housing Options in Nearby Communities
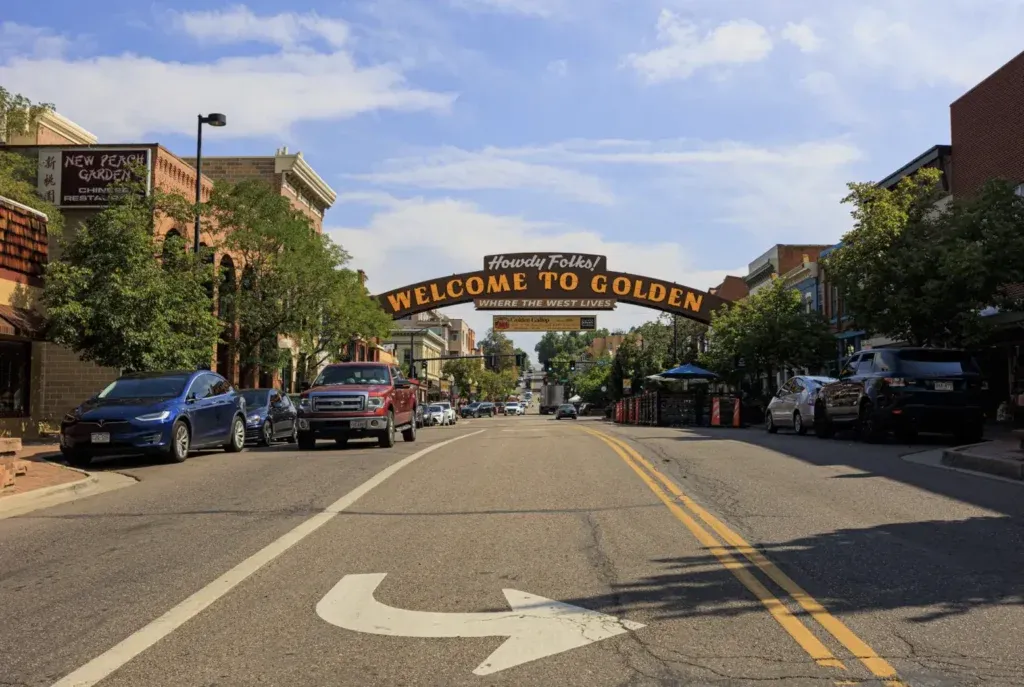
Some buyers search beyond Denver when evaluating residential properties. Lakewood, Arvada, Golden, Littleton, and Centennial are among the surrounding communities that buyers may consider. Each offers different housing types, locations, and available properties. Expanding your search may provide additional options, depending on your budget and requirements.
Searching for Homes for Sale in Denver
Once your financing and preferred areas are established, you can begin searching for available properties. A structured approach makes it easier to compare homes and identify suitable options.
Identify Your Property Requirements
Consider the features you need in your next home. Bedroom count, bathrooms, parking, storage, outdoor space, and accessibility may all influence your decision. It is useful to distinguish essential requirements from preferred features. For example, a household may require three bedrooms but have flexibility regarding kitchen finishes.
This allows buyers to evaluate a broader range of properties without losing focus on their priorities.
Review Online Home Listings
Online listings provide information about available properties. Photographs, descriptions, floor plans, and property characteristics can help you identify homes worth visiting. However, listing information may be incomplete. Important details should be verified before making financial commitments.
Schedule Property Tours
Visiting homes allows buyers to evaluate their condition and layout. Consider whether the available space meets your needs. Pay attention to visible maintenance issues, storage, natural lighting, and general functionality. A property may look attractive in photographs but feel different during an in-person visit.
What to Look for When Viewing a House
A home showing is an opportunity to examine the property and ask questions. While a showing does not replace a professional inspection, buyers can identify areas that may require further evaluation.
Exterior Property Condition
Review the visible condition of the roof, siding, walkways, landscaping, and drainage areas. Look for obvious damage or signs of neglected maintenance. Some issues may be relatively minor, while others require professional assessment. Avoid making conclusions about structural condition based only on appearance.
Heating, Cooling, and Plumbing
Ask about the age and maintenance history of major systems. Heating equipment is an important consideration for Colorado homeowners. Plumbing leaks, damaged fixtures, and other visible problems may also require attention. A qualified inspector can provide a more detailed evaluation.
Interior Layout and Storage
Consider whether the floor plan supports your daily activities. Evaluate bedroom sizes, kitchen functionality, closet space, and storage. A property with sufficient square footage may still have a layout that does not fit your needs. Think about how the available rooms would be used rather than focusing only on their appearance.
How to Make an Offer on a House in Denver
After finding a suitable property, the next step is preparing a purchase offer. The offer should reflect the home’s market value, your financing arrangements, and the terms you are comfortable accepting.
Determine a Reasonable Purchase Price
Review recent comparable sales before deciding how much to offer. Consider the property’s condition and how it compares with active listings. The asking price is an important reference, but it does not automatically establish market value. An offer should reflect your financial limits and available market evidence.
Understand Earnest Money
Earnest money is generally a deposit provided according to the purchase agreement. The contract determines how the deposit is held and the conditions under which it may be returned or forfeited. Buyers should understand these terms before signing.
Review Purchase Contract Contingencies
Purchase agreements may include conditions related to inspections, financing, appraisals, and title matters. These provisions can affect how the transaction proceeds. The contract also establishes important deadlines. Buyers should understand the consequences of missing a deadline or failing to meet a contractual requirement.
Understanding Home Inspections in Colorado
A professional home inspection can provide information about the property’s condition before closing. Inspections may identify maintenance problems, safety concerns, or issues requiring additional investigation.
What Does a Home Inspection Include?
A standard residential inspection generally reviews accessible components of the property. These may include the roof, foundation, heating and cooling systems, plumbing, electrical components, and other visible features. The inspection scope varies depending on the professional and services requested. Not every defect can be identified during a standard inspection.
Why Inspections Matter for Buyers
A property may have problems that are not obvious during a regular showing. An inspection report provides information that can help buyers understand possible repair needs. Some findings may require evaluation by specialized contractors. Buyers should review the report carefully before making decisions under the purchase agreement.
Can Buyers Request Repairs?
Depending on the contract, buyers may request repairs, financial concessions, or other arrangements following an inspection. The seller may accept, reject, or negotiate requests as permitted by the agreement. The transaction outcome depends on the contract terms and the parties’ decisions.
What Is a Home Appraisal?
A home appraisal is an independent opinion of property value. Mortgage lenders commonly require an appraisal before approving certain residential loans.
How the Appraisal Process Works
An appraiser evaluates the property and relevant market information. The assessment may consider location, condition, size, and comparable sales. The appraisal helps the lender evaluate the property’s value for financing purposes.
What Happens if the Appraisal Is Lower Than the Purchase Price?
A lower appraisal can affect the amount a lender is willing to finance. The buyer and seller may need to discuss the purchase terms or other options. The result depends on the financing arrangement and purchase contract. Buyers should understand the applicable appraisal provisions before making an offer.
Understanding Closing Costs When Buying a Home
In addition to the down payment, buyers should budget for closing expenses. These costs vary according to the loan, property, service providers, and purchase agreement.
Common Home Buyer Closing Costs
Closing expenses may include lender fees, appraisal charges, title services, recording costs, insurance, and prepaid expenses. Some charges may be paid before closing. Others are included in the final settlement. The total depends on the specific transaction.
Review Your Loan Estimate
A Loan Estimate provides information about the proposed mortgage, including estimated payments and closing expenses. Review the figures carefully. Comparing estimates from different lenders can help identify differences in financing costs.
Understand Your Closing Disclosure
For most covered mortgages, the lender must provide a Closing Disclosure at least three business days before consummation. This document explains the final loan terms and closing costs. Buyers should compare it with earlier estimates and ask about unexpected changes.
What Happens on Closing Day?
Closing is the final stage of the home buying process. The parties complete the required documents and financial arrangements according to the purchase agreement.
Review the Final Documents
Buyers may need to sign mortgage documents, settlement statements, and other required paperwork. Read important information carefully before signing. Ask the lender or settlement professional to explain anything you do not understand.
Confirm Your Final Payment
Your required closing funds should match the applicable settlement information. Payment instructions should be verified through trusted contact details to reduce the risk of fraud. Unexpected changes in wiring instructions should be independently confirmed.
Receiving the Keys to Your New Home
The purchase contract determines when the buyer receives possession. Possession may occur at closing or at another agreed time. Confirm the arrangements before scheduling moving services.
Common Mistakes First-time Home Buyers Should Avoid
Buying your first property involves several important financial decisions. Avoiding common mistakes can help reduce complications during the transaction.
Buying More House Than You Can Afford
Mortgage preapproval does not mean you should spend the maximum approved amount. Consider your monthly expenses, savings goals, and maintenance responsibilities. A manageable housing budget is important for long-term financial stability.
Ignoring Additional Ownership Expenses
Property taxes, insurance, utilities, repairs, and homeowners association fees can increase monthly housing expenses. Buyers should consider these costs before making an offer.
Skipping Important Inspections
A home’s appearance does not always reflect the condition of its major systems. Professional inspections can provide useful information before completing a purchase.
Making Major Financial Changes Before Closing
Taking on additional debt or making significant financial changes may affect mortgage approval. Discuss major financial decisions with your lender while the loan is being processed.
Build a Denver home-buying brief before touring
Give your search a written starting point. List the rooms you actually need, your parking and storage requirements, the activities you want nearby, and the payment you want to live with. Separate requirements from preferences so that a beautiful photograph does not quietly rewrite your priorities. Ask everyone involved in the purchase to make this distinction independently, then compare answers before booking showings.
Make your location questions specific enough to test. Instead of asking whether a community has a good commute, identify your destination, departure time, and transportation method. Instead of treating a school reference in a listing as a guarantee, verify the address with the relevant district. Walk the immediate block, review access to your usual errands, and decide which trade-offs you would still accept after the excitement of a showing has passed.
Use the Colorado community guides to organize your research, then use the home-comparison tool to record the same questions for each property. Keep unknown answers marked as unknown. A useful comparison is honest about its gaps instead of giving every home a confident score based on incomplete information.
What should you investigate beyond the standard showing?
A showing is a first look, not the end of due diligence. Treat the following as a conversation checklist for your agent and qualified professionals. It is not a diagnosis of the property or a substitute for the inspection scope and deadlines you agree to in writing.
| Question to investigate | Information to request | Who can help |
|---|---|---|
| Roof and exterior | Available repair records, known damage, and access for an inspection | Inspector and appropriate contractor |
| Below-grade space | Observed moisture, prior repairs, and intended use of finished or unfinished areas | Inspector and relevant specialist |
| Radon | Testing history, any mitigation records, and a plan for a current test | Licensed radon professional |
| Association obligations | Current documents, charges, maintenance responsibilities, and pending issues to review | Association, agent, lender, and legal counsel as appropriate |
| Insurance | A property-specific quote and explanation of deductibles, limitations, and coverage | Licensed insurance professional |
Colorado’s public-health department encourages buyers to test for radon during the inspection process, including homes where a mitigation system may already be present (Colorado public-health guidance on radon testing). Arrange the scope and timing with the relevant professionals rather than assuming a general inspection automatically includes every test you want.
For most homes built before 1978, federal lead-disclosure requirements include providing known information and available reports before the buyer signs a contract (EPA guidance on lead-based paint disclosures). Ask your agent what applies to the particular property and what documents should be reviewed. Do not assume new paint answers the question.
Turn your accepted offer into a working calendar
After an offer is accepted, create one calendar with the actual dates from the executed agreement. Give each item an owner, the information needed to complete it, and the person who must receive the response. Ask your agent to walk you through the contract rather than relying on a generic online timeline. Colorado publishes separate residential contract, disclosure, and related transaction forms through the Colorado Division of Real Estate forms.
Make room for reviewing information, not just ordering it. For example, receiving an inspection report is different from discussing its findings with an inspector and deciding how to respond. Receiving association documents is different from understanding an unfamiliar assessment or maintenance obligation. Schedule those conversations early enough to make an informed decision under your agreement.
The Closing Disclosure provides final mortgage terms, projected payments, and closing costs, and covered borrowers must receive it at least three business days before closing (CFPB explanation of the Closing Disclosure). Compare it with your most recent Loan Estimate and ask your lender about discrepancies. Confirm possession separately with your agent, then coordinate utilities, movers, access devices, and the final walkthrough around that agreement.
Before committing your entire cash reserve, use the homeownership-budget guide to review the expenses that begin after the purchase. Bring the unresolved questions to a buyer consultation so your next step is based on your actual circumstances.
Frequently Asked Questions About Buying a House in Denver
How Much Money Do I Need to Buy a House in Denver?
The required amount depends on the purchase price, down payment, mortgage program, and closing expenses. A lender can help estimate the cash needed for your specific financing arrangement.
Is Denver a Good Place for First-time Home Buyers?
Denver offers different housing options and neighborhoods. Whether it is suitable depends on your budget, housing requirements, and financial circumstances. Researching available properties can help you decide.
Can I Buy a House in Denver With Less Than 20 Percent Down?
Some mortgage programs allow qualifying buyers to purchase with a down payment below 20 percent. Eligibility and associated costs depend on the lender and financing program.
Do I Need a Real Estate Agent to Buy a Home?
Hiring a real estate agent is not universally required. However, a qualified agent can assist with property searches, comparable sales, contract discussions, and transaction coordination. Buyers should understand representation terms before signing an agreement.
How Long Does It Take to Buy a House in Denver?
The timeline depends on property availability, financing, inspection requirements, and the contract. Delays can occur during mortgage underwriting, title review, or other transaction stages.
Should I Get Preapproved Before Searching for Homes?
Mortgage preapproval is generally a useful early step. It helps buyers understand potential financing options and establish a realistic search range.
Find Your Next Home With Ed Prather Real Estate
Buying a house in Denver requires careful financial planning, local market research, and an understanding of the real estate transaction process. From reviewing mortgage options and searching for suitable properties to evaluating offers and completing closing requirements, each step deserves attention. Ed Prather Real Estate helps buyers explore available homes throughout Denver, Lakewood, and surrounding Colorado communities.
Whether you are a first-time home buyer or preparing for another property purchase, understanding your budget and local housing options can help you make informed decisions.
Start Searching for Homes in Denver Today
Contact Ed Prather Real Estate to explore available properties, discuss your home buying goals, and learn more about purchasing a home in Denver, CO.
Make this advice personal.
Tell the team about your next move and get guidance for your situation.
This guide provides general planning information, not individualized legal, tax, insurance, or lending advice. Confirm the requirements, documents, deadlines, and costs for your transaction with the appropriate professionals.